Portfolio Optimization

No Country for Old Means: Optimal Input Shrinkage for Optimal Portfolios?

We price the shrinkage of the mean when the covariance matrix it relies on is itself estimated. The best shrinkage intensity follows from the number of assets and the length of the …

Sebastian Stöckl
•

Risk-Adjusted Forecast Performance

Closing the gap between statistical forecast accuracy and the Sharpe ratio investors actually care about.

Factor Investing & Factor Timing

Methods for selecting, timing, and combining factors when the zoo is crowded, the cross-section is noisy, and estimation error dominates.

Lost in Translation? Risk-Adjusting RMSE for Economic Forecast Performance featured image

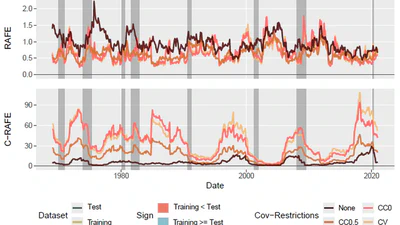
Lost in Translation? Risk-Adjusting RMSE for Economic Forecast Performance

This paper proposes a multivariate risk-adjusted error measure for economic forecast performance and analyzes the limitations of traditional MSE-based measures in capturing the …

lukas-salcher
•

Diversifying Estimation Errors with Unsupervised Machine Learning

Unsupervised ML clustering of assets into equally weighted sub-portfolios dominates both plug-in minimum variance and equally weighted benchmarks, with optimal cluster count around …

merlin-bartel
•