PhD Project

Less Is More: Forecast Granularity, Estimation Error, and Portfolio Choice featured image

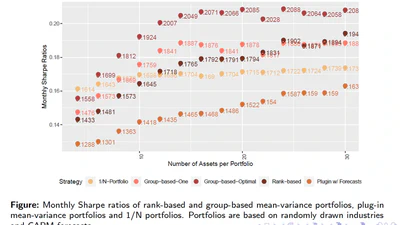
Less Is More: Forecast Granularity, Estimation Error, and Portfolio Choice

Each dimension of a return forecast an investor acts on costs 1/T, whatever signal it carries. Setting the number of rank groups from the forecast's information coefficient, and …

lukas-salcher
•
Factor Chasing and the Cross-Country Factor Momentum Anomaly featured image

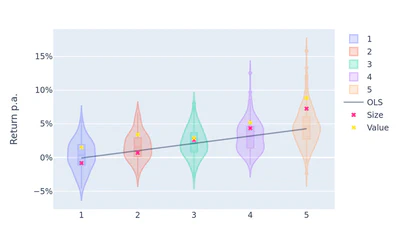
Factor Chasing and the Cross-Country Factor Momentum Anomaly

We document a cross-country factor momentum anomaly, which we term 'Factor Chasing'. Specialized style mutual funds chase factor returns across countries, but their trades are …

pedro-barroso
•