Higher Moments Matter! Cross-Sectional (Higher) Moments and the Predictability of Stock Returns
In this paper we investigate the predictive power of cross-sectional volatility, skewness and kurtosis for future stock returns.
Sebastian Stöckl
In this paper we investigate the predictive power of cross-sectional volatility, skewness and kurtosis for future stock returns.
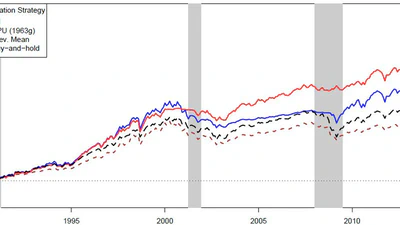
In this paper, we develop a novel, intuitive and objective measure of time-varying parameter uncertainty (PU) based on a simple statistical test.
Do forecasting errors from direct predictions of market components out-way the additional errors introduced by an intermediary asset pricing model?