Estimation Errors

Less Is More: Forecast Granularity, Estimation Error, and Portfolio Choice featured image

Less Is More: Forecast Granularity, Estimation Error, and Portfolio Choice

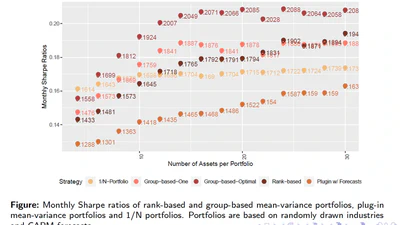
Each dimension of a return forecast an investor acts on costs 1/T, whatever signal it carries. Setting the number of rank groups from the forecast's information coefficient, and …

lukas-salcher
•

Diversifying Estimation Errors with Unsupervised Machine Learning

Unsupervised ML clustering of assets into equally weighted sub-portfolios dominates both plug-in minimum variance and equally weighted benchmarks, with optimal cluster count around …

merlin-bartel
•