Breaking Bad: Parameter Uncertainty Caused by Structural Breaks in Stocks
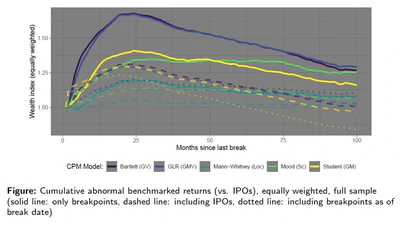
This paper introduces break-age, a novel measure for parameter uncertainty caused by structural breaks, and demonstrates its significance in stock pricing.
lukas-salcher
This paper introduces break-age, a novel measure for parameter uncertainty caused by structural breaks, and demonstrates its significance in stock pricing.
We estimate crypto-related risk for U.S. banks using historical covariance with bitcoin returns, focusing on contagion from FTX's failure.
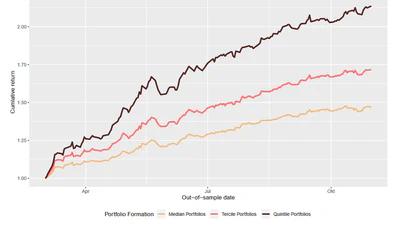
Unsupervised ML clustering of assets into equally weighted sub-portfolios dominates both plug-in minimum variance and equally weighted benchmarks, with optimal cluster count around …
Correcting for survivorship and delisting bias substantially overturns published cryptocurrency anomaly evidence: size is overstated, while momentum and market beta no longer price …
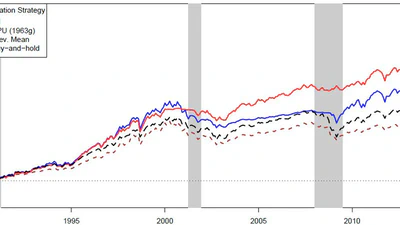
In this paper, we develop a novel, intuitive and objective measure of time-varying parameter uncertainty (PU) based on a simple statistical test.
We show that parameter uncertainty based on the turbulence within each cross-section of factor portfolios produces a significant out-of-sample forecast for six out of seven tested …
Based on a multidisciplinary literature review, we discuss the assumptions implicit in the prevalent Black-Scholes model and argue for relaxed assumptions that better represent …
Do forecasting errors from direct predictions of market components out-way the additional errors introduced by an intermediary asset pricing model?