Manuscript

Industry Positions in Characteristic Factors: Risk Without Return

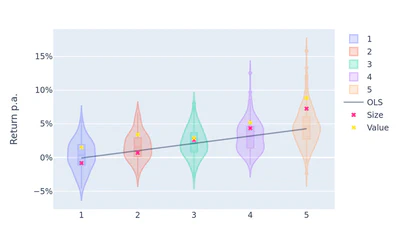
Sorting on a characteristic buys an industry bet nobody asked for: 18 percent of a factor's variance, 0.3 percent a year. Ranking within industries removes it without estimating a …

christoph-reschenhofer
•

No Country for Old Means: Optimal Input Shrinkage for Optimal Portfolios?

We price the shrinkage of the mean when the covariance matrix it relies on is itself estimated. The best shrinkage intensity follows from the number of assets and the length of the …

Sebastian Stöckl
•
Less Is More: Forecast Granularity, Estimation Error, and Portfolio Choice featured image

Less Is More: Forecast Granularity, Estimation Error, and Portfolio Choice

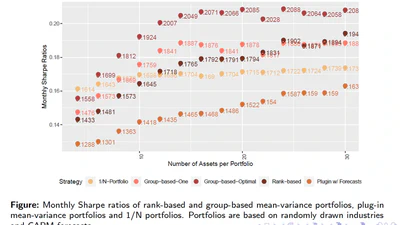
Each dimension of a return forecast an investor acts on costs 1/T, whatever signal it carries. Setting the number of rank groups from the forecast's information coefficient, and …

lukas-salcher
•

The Event Clock: Identifying Physical Information from State Prices

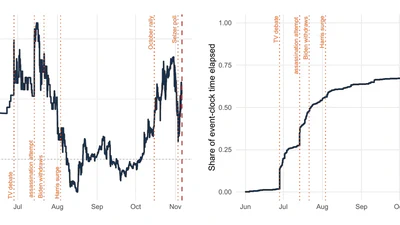
How much of the price variation ahead of a scheduled event reflects genuine learning rather than valuation shocks? Three prediction-market venues identify the learning-spanned …

michael-hanke
•

The Theme Structure of Factor Momentum

The factor zoo's 153 long-short factors reduce to about thirteen near-uncorrelated themes. Factor momentum survives that compression, and its profits come from persistence within …

Sebastian Stöckl
•
The Milei Question, or: How Liberal Are Right-Wing Populist Parties? A Measurement Approach Using Large Language Models featured image

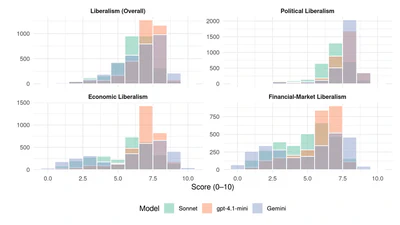
The Milei Question, or: How Liberal Are Right-Wing Populist Parties? A Measurement Approach Using Large Language Models

Large language models are used to score populist rhetoric and four dimensions of liberalism across party manifestos, showing that right-wing populist anti-liberalism is largely …

Martin Rode
•
Learning Before Scheduled Events: Prediction Markets, State Prices, and Option Valuation featured image

Learning Before Scheduled Events: Prediction Markets, State Prices, and Option Valuation

Options spanning a scheduled event are priced from observed event-clock inputs, with sequential overidentification restrictions tested on the Brexit referendum and on 2024 U.S. …

michael-hanke
•
Are There Fences in the Global Factor Zoo? featured image

Are There Fences in the Global Factor Zoo?

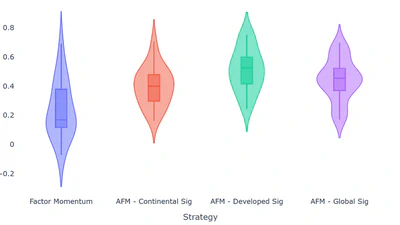
Regional and global factor momentum signals outperform local factors in forecasting risk premiums and revitalize momentum investing in less-integrated markets like Japan.

merlin-bartel
•
Stochastic Event-Outcome Probabilities and the Pricing of Scheduled Event Risk featured image

Stochastic Event-Outcome Probabilities and the Pricing of Scheduled Event Risk

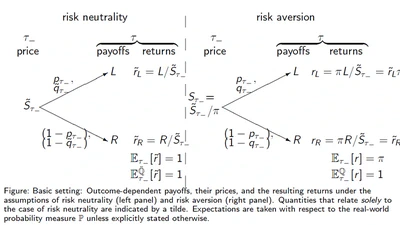
We analyze event risk premia in an expected utility framework and provide closed-form solutions under both quadratic and power utility for four different cases: …

michael-hanke
•
Factor Chasing and the Cross-Country Factor Momentum Anomaly featured image

Factor Chasing and the Cross-Country Factor Momentum Anomaly

We document a cross-country factor momentum anomaly, which we term 'Factor Chasing'. Specialized style mutual funds chase factor returns across countries, but their trades are …

pedro-barroso
•